Impact on credit score of opening and closing accounts Announcing the arrival of Valued Associate #679: Cesar Manara Planned maintenance scheduled April 17/18, 2019 at 00:00UTC (8:00pm US/Eastern) Frequently Answered Questions (by topic) Can we remove “Strategies for earning more money” from the on-topic list?Experian credit report: what are major credit cards?Is it a bad idea to have 3 secured credit card accounts open?Should I close my BestBuy Credit Card? Will it affect my credit score and history?Am I using my credit card wrong?Why was my Credit Limit Increase Denied?Optimal number of credit cards for a given length of credit historyDoes LendingClub's quick screening impact credit score?Does closing accounts lower one's credit score?Will the AMEX to CitiBank portfolio sale affect my credit score?Does opening credit cards at different banks impact credit score?
What does the "x" in "x86" represent?
Irreducible of finite Krull dimension implies quasi-compact?
What do you call the main part of a joke?
Is there any way for the UK Prime Minister to make a motion directly dependent on Government confidence?
First console to have temporary backward compatibility
Can melee weapons be used to deliver Contact Poisons?
Do I really need recursive chmod to restrict access to a folder?
Is it ethical to give a final exam after the professor has quit before teaching the remaining chapters of the course?
How to down pick a chord with skipped strings?
How to tell that you are a giant?
What's the meaning of "fortified infraction restraint"?
Why do we bend a book to keep it straight?
Quick way to create a symlink?
How to answer "Have you ever been terminated?"
What does "lightly crushed" mean for cardamon pods?
Significance of Cersei's obsession with elephants?
Can anything be seen from the center of the Boötes void? How dark would it be?
Is "Reachable Object" really an NP-complete problem?
Extracting terms with certain heads in a function
Is there a holomorphic function on open unit disc with this property?
Using audio cues to encourage good posture
Wu formula for manifolds with boundary
Did MS DOS itself ever use blinking text?
How can I use the Python library networkx from Mathematica?
Impact on credit score of opening and closing accounts
Announcing the arrival of Valued Associate #679: Cesar Manara
Planned maintenance scheduled April 17/18, 2019 at 00:00UTC (8:00pm US/Eastern)
Frequently Answered Questions (by topic)
Can we remove “Strategies for earning more money” from the on-topic list?Experian credit report: what are major credit cards?Is it a bad idea to have 3 secured credit card accounts open?Should I close my BestBuy Credit Card? Will it affect my credit score and history?Am I using my credit card wrong?Why was my Credit Limit Increase Denied?Optimal number of credit cards for a given length of credit historyDoes LendingClub's quick screening impact credit score?Does closing accounts lower one's credit score?Will the AMEX to CitiBank portfolio sale affect my credit score?Does opening credit cards at different banks impact credit score?
.everyoneloves__top-leaderboard:empty,.everyoneloves__mid-leaderboard:empty,.everyoneloves__bot-mid-leaderboard:empty margin-bottom:0;
I'm planning on buying a house sometime in the Winter of 2020 to spring 2021.
Currently, my credit score is about 770 and I have the following open credit lines:
- A 2.5 year old $25,000 Prosper loan with a $12,000 balance with 2.5 years to go.
- A gold American Express that has been open since 1998
- A First National Bank American Express with $0 balance, $12,000 limit open since 2013
- A Visa card with $0 balance, $4100 limit open since 2013
- A Citibank Mastercard, $11,000 balance, $25,000 limit, open since 2013
- A Citibank Mastercard, $0 balance, $11,000 limit, open since 2014
So, about $77,100 available of which $23,000 is used or about 30% utilizaton
I am paying down the open lines and should be finished with that by the end of the year.
I never use the $4100 Visa or the First National Bank AmEx. And, I received an offer for a $10,000 limit Visa at %9.15 from my credit union.
That is a substantially better rate than any of my other cards and I was considering closing both of the unused accounts. This would result in:
$71,000 available, $23,000 used and 32.39% utilization.
So, doing this will increase my utilization, lower the average age of my credit, and result in a hard query on my account.
I have 2 questions:
- Is there a way to determine how much doing this will lower my score?
- If I do it, will my score recover by the winter of 2020 when I start looking for home loans.
Any insight that you can provide would be appreciated.
credit-score credit credit-report credit-history
edited 4 hours ago

yoozer8
2,28841123
asked 4 hours ago
Rex ChandlerRex Chandler
802
add a comment |
I'm planning on buying a house sometime in the Winter of 2020 to spring 2021.
Currently, my credit score is about 770 and I have the following open credit lines:
- A 2.5 year old $25,000 Prosper loan with a $12,000 balance with 2.5 years to go.
- A gold American Express that has been open since 1998
- A First National Bank American Express with $0 balance, $12,000 limit open since 2013
- A Visa card with $0 balance, $4100 limit open since 2013
- A Citibank Mastercard, $11,000 balance, $25,000 limit, open since 2013
- A Citibank Mastercard, $0 balance, $11,000 limit, open since 2014
So, about $77,100 available of which $23,000 is used or about 30% utilizaton
I am paying down the open lines and should be finished with that by the end of the year.
I never use the $4100 Visa or the First National Bank AmEx. And, I received an offer for a $10,000 limit Visa at %9.15 from my credit union.
That is a substantially better rate than any of my other cards and I was considering closing both of the unused accounts. This would result in:
$71,000 available, $23,000 used and 32.39% utilization.
So, doing this will increase my utilization, lower the average age of my credit, and result in a hard query on my account.
I have 2 questions:
- Is there a way to determine how much doing this will lower my score?
- If I do it, will my score recover by the winter of 2020 when I start looking for home loans.
Any insight that you can provide would be appreciated.
credit-score credit credit-report credit-history
edited 4 hours ago
yoozer8
2,28841123
asked 4 hours ago
Rex ChandlerRex Chandler
802
2
Is the only reason you want to get the new card because it has a better rate? If you're paying off cards on time (as you should) and not carrying a balance, then the rate is inconsequential.
– Nosjack
4 hours ago
Care to share how you know your current score? Is it an actual FICO or an estimated one from a third party?
– JoeTaxpayer♦
3 hours ago
add a comment |
I'm planning on buying a house sometime in the Winter of 2020 to spring 2021.
Currently, my credit score is about 770 and I have the following open credit lines:
- A 2.5 year old $25,000 Prosper loan with a $12,000 balance with 2.5 years to go.
- A gold American Express that has been open since 1998
- A First National Bank American Express with $0 balance, $12,000 limit open since 2013
- A Visa card with $0 balance, $4100 limit open since 2013
- A Citibank Mastercard, $11,000 balance, $25,000 limit, open since 2013
- A Citibank Mastercard, $0 balance, $11,000 limit, open since 2014
So, about $77,100 available of which $23,000 is used or about 30% utilizaton
I am paying down the open lines and should be finished with that by the end of the year.
I never use the $4100 Visa or the First National Bank AmEx. And, I received an offer for a $10,000 limit Visa at %9.15 from my credit union.
That is a substantially better rate than any of my other cards and I was considering closing both of the unused accounts. This would result in:
$71,000 available, $23,000 used and 32.39% utilization.
So, doing this will increase my utilization, lower the average age of my credit, and result in a hard query on my account.
I have 2 questions:
- Is there a way to determine how much doing this will lower my score?
- If I do it, will my score recover by the winter of 2020 when I start looking for home loans.
Any insight that you can provide would be appreciated.
credit-score credit credit-report credit-history
edited 4 hours ago
yoozer8
2,28841123
asked 4 hours ago
Rex ChandlerRex Chandler
802
I'm planning on buying a house sometime in the Winter of 2020 to spring 2021.
Currently, my credit score is about 770 and I have the following open credit lines:
- A 2.5 year old $25,000 Prosper loan with a $12,000 balance with 2.5 years to go.
- A gold American Express that has been open since 1998
- A First National Bank American Express with $0 balance, $12,000 limit open since 2013
- A Visa card with $0 balance, $4100 limit open since 2013
- A Citibank Mastercard, $11,000 balance, $25,000 limit, open since 2013
- A Citibank Mastercard, $0 balance, $11,000 limit, open since 2014
So, about $77,100 available of which $23,000 is used or about 30% utilizaton
I am paying down the open lines and should be finished with that by the end of the year.
I never use the $4100 Visa or the First National Bank AmEx. And, I received an offer for a $10,000 limit Visa at %9.15 from my credit union.
That is a substantially better rate than any of my other cards and I was considering closing both of the unused accounts. This would result in:
$71,000 available, $23,000 used and 32.39% utilization.
So, doing this will increase my utilization, lower the average age of my credit, and result in a hard query on my account.
I have 2 questions:
- Is there a way to determine how much doing this will lower my score?
- If I do it, will my score recover by the winter of 2020 when I start looking for home loans.
Any insight that you can provide would be appreciated.
credit-score credit credit-report credit-history
credit-score credit credit-report credit-history
edited 4 hours ago
yoozer8
2,28841123
asked 4 hours ago
Rex ChandlerRex Chandler
802
edited 4 hours ago
yoozer8
2,28841123
asked 4 hours ago
Rex ChandlerRex Chandler
802
edited 4 hours ago
yoozer8
2,28841123
edited 4 hours ago
yoozer8
2,28841123
edited 4 hours ago
yoozer8
2,28841123
2,28841123
asked 4 hours ago
Rex ChandlerRex Chandler
802
asked 4 hours ago
Rex ChandlerRex Chandler
802
asked 4 hours ago
Rex ChandlerRex Chandler
802
802
2
Is the only reason you want to get the new card because it has a better rate? If you're paying off cards on time (as you should) and not carrying a balance, then the rate is inconsequential.
– Nosjack
4 hours ago
Care to share how you know your current score? Is it an actual FICO or an estimated one from a third party?
– JoeTaxpayer♦
3 hours ago
add a comment |
2
Is the only reason you want to get the new card because it has a better rate? If you're paying off cards on time (as you should) and not carrying a balance, then the rate is inconsequential.
– Nosjack
4 hours ago
Care to share how you know your current score? Is it an actual FICO or an estimated one from a third party?
– JoeTaxpayer♦
3 hours ago
2
2
Is the only reason you want to get the new card because it has a better rate? If you're paying off cards on time (as you should) and not carrying a balance, then the rate is inconsequential.
– Nosjack
4 hours ago
Is the only reason you want to get the new card because it has a better rate? If you're paying off cards on time (as you should) and not carrying a balance, then the rate is inconsequential.
– Nosjack
4 hours ago
Care to share how you know your current score? Is it an actual FICO or an estimated one from a third party?
– JoeTaxpayer♦
3 hours ago
Care to share how you know your current score? Is it an actual FICO or an estimated one from a third party?
– JoeTaxpayer♦
3 hours ago
add a comment |
2 Answers
2
active
oldest
votes
Despite what the lender funded media suggests you should close un-utilized accounts and get that Prosper loan and credit card paid off ASAP. If it were me, at most, I would keep the AMEX and one other card. By the time you are ready to buy a home your score will be the highest possible.
This exactly happened to me and many others I have spoken with. Pay off your debt, close accounts and your score skyrockets.
However, this really doesn't matter. Anything above 730 is vanity. Your go/no go decision will all be income and down payment based.
In summary the best thing you can do, in order, is:
- Pay off that credit card and Prosper loan.
- Save a down payment of 20%
- Close credit card accounts
- Save even more
edited 3 hours ago

JoeTaxpayer♦
148k23238478
answered 4 hours ago

Pete B.Pete B.
52.6k13111164
740 and 760 are frequently used as cutoffs for 'excellent' credit, so maybe some real benefit to getting over 730, but the point is valid that above some number it doesn't do much if any good to have a higher score.
– Hart CO
2 hours ago
add a comment |
Call me vain, but when it took me a ten minute phone call to get a $250K HELOC approved with no tax returns and no income (literally, we are retired), I'll wear my 850 FICO score on my hat.
You are in great shape. Be mindful of the factors that make up your score.
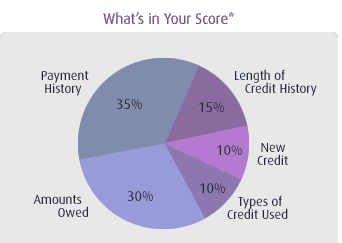
Adding the new card will -
- Lower your utilization
- Lower your credit history (# of years average account age)
- Add an inquiry/ New Credit
Killing an old card will
- Raise utilization
- Lower average account age
You really have 2 issues. The first is whether to get the new card. Yes. Of course. Lowering your current interest burden is quantifiable, you can calculate the savings, and have a relatively low interest source of cash.
The second is what to get rid of. All due respect to @PeteB I'd wait before getting rid of any current cards for the reason above. I happen to use Credit Karma to track my score, and am able to see impact from adding a card or removing one. I carry no debt, and after getting a grip on the fact that running my expenses through credit cards will show a 'balance' so I pay in full before the balance is reported, I'm still careful with which accounts I'll add or remove. As long as the unused card carry no fee, I'd wait until after the mortgage is closed. Long term, the goal should be to have only cards that provide a unique benefit. I have one with 2% cash on all purchases. Another with 5% back on Amazon. Etc.
After you have your mortgage, I'd review the benefits of each card you have, and figure out a strategy moving forward. For example, the last card I got gave me $1200 worth of miles for my first $1000 worth of spending. (The kid transferred colleges, so that card may not be useful for long, but it was worth the effort for the return I got).
answered 2 hours ago
JoeTaxpayer♦JoeTaxpayer
148k23238478
add a comment |
Your Answer
StackExchange.ready(function()
var channelOptions =
tags: "".split(" "),
id: "93"
;
initTagRenderer("".split(" "), "".split(" "), channelOptions);
StackExchange.using("externalEditor", function()
// Have to fire editor after snippets, if snippets enabled
if (StackExchange.settings.snippets.snippetsEnabled)
StackExchange.using("snippets", function()
createEditor();
);
else
createEditor();
);
function createEditor()
StackExchange.prepareEditor(
heartbeatType: 'answer',
autoActivateHeartbeat: false,
convertImagesToLinks: true,
noModals: true,
showLowRepImageUploadWarning: true,
reputationToPostImages: 10,
bindNavPrevention: true,
postfix: "",
imageUploader:
brandingHtml: "Powered by u003ca class="icon-imgur-white" href="https://imgur.com/"u003eu003c/au003e",
contentPolicyHtml: "User contributions licensed under u003ca href="https://creativecommons.org/licenses/by-sa/3.0/"u003ecc by-sa 3.0 with attribution requiredu003c/au003e u003ca href="https://stackoverflow.com/legal/content-policy"u003e(content policy)u003c/au003e",
allowUrls: true
,
noCode: true, onDemand: true,
discardSelector: ".discard-answer"
,immediatelyShowMarkdownHelp:true
);
);
Sign up or log in
StackExchange.ready(function ()
StackExchange.helpers.onClickDraftSave('#login-link');
);
Sign up using Google
Sign up using Facebook
Sign up using Email and Password
Post as a guest
Required, but never shown
StackExchange.ready(
function ()
StackExchange.openid.initPostLogin('.new-post-login', 'https%3a%2f%2fmoney.stackexchange.com%2fquestions%2f107949%2fimpact-on-credit-score-of-opening-and-closing-accounts%23new-answer', 'question_page');
);
Post as a guest
Required, but never shown
2 Answers
2
active
oldest
votes
2 Answers
2
active
oldest
votes
active
oldest
votes
active
oldest
votes
Despite what the lender funded media suggests you should close un-utilized accounts and get that Prosper loan and credit card paid off ASAP. If it were me, at most, I would keep the AMEX and one other card. By the time you are ready to buy a home your score will be the highest possible.
This exactly happened to me and many others I have spoken with. Pay off your debt, close accounts and your score skyrockets.
However, this really doesn't matter. Anything above 730 is vanity. Your go/no go decision will all be income and down payment based.
In summary the best thing you can do, in order, is:
- Pay off that credit card and Prosper loan.
- Save a down payment of 20%
- Close credit card accounts
- Save even more
edited 3 hours ago
JoeTaxpayer♦
148k23238478
answered 4 hours ago
Pete B.Pete B.
52.6k13111164
740 and 760 are frequently used as cutoffs for 'excellent' credit, so maybe some real benefit to getting over 730, but the point is valid that above some number it doesn't do much if any good to have a higher score.
– Hart CO
2 hours ago
add a comment |
Despite what the lender funded media suggests you should close un-utilized accounts and get that Prosper loan and credit card paid off ASAP. If it were me, at most, I would keep the AMEX and one other card. By the time you are ready to buy a home your score will be the highest possible.
This exactly happened to me and many others I have spoken with. Pay off your debt, close accounts and your score skyrockets.
However, this really doesn't matter. Anything above 730 is vanity. Your go/no go decision will all be income and down payment based.
In summary the best thing you can do, in order, is:
- Pay off that credit card and Prosper loan.
- Save a down payment of 20%
- Close credit card accounts
- Save even more
edited 3 hours ago
JoeTaxpayer♦
148k23238478
answered 4 hours ago
Pete B.Pete B.
52.6k13111164
edited 3 hours ago
JoeTaxpayer♦
148k23238478
edited 3 hours ago
JoeTaxpayer♦
148k23238478
edited 3 hours ago
JoeTaxpayer♦
148k23238478
148k23238478
answered 4 hours ago
Pete B.Pete B.
52.6k13111164
answered 4 hours ago
Pete B.Pete B.
52.6k13111164
answered 4 hours ago
Pete B.Pete B.
52.6k13111164
52.6k13111164
740 and 760 are frequently used as cutoffs for 'excellent' credit, so maybe some real benefit to getting over 730, but the point is valid that above some number it doesn't do much if any good to have a higher score.
– Hart CO
2 hours ago
add a comment |
740 and 760 are frequently used as cutoffs for 'excellent' credit, so maybe some real benefit to getting over 730, but the point is valid that above some number it doesn't do much if any good to have a higher score.
– Hart CO
2 hours ago
740 and 760 are frequently used as cutoffs for 'excellent' credit, so maybe some real benefit to getting over 730, but the point is valid that above some number it doesn't do much if any good to have a higher score.
– Hart CO
2 hours ago
740 and 760 are frequently used as cutoffs for 'excellent' credit, so maybe some real benefit to getting over 730, but the point is valid that above some number it doesn't do much if any good to have a higher score.
– Hart CO
2 hours ago
add a comment |
Call me vain, but when it took me a ten minute phone call to get a $250K HELOC approved with no tax returns and no income (literally, we are retired), I'll wear my 850 FICO score on my hat.
You are in great shape. Be mindful of the factors that make up your score.
Adding the new card will -
- Lower your utilization
- Lower your credit history (# of years average account age)
- Add an inquiry/ New Credit
Killing an old card will
- Raise utilization
- Lower average account age
You really have 2 issues. The first is whether to get the new card. Yes. Of course. Lowering your current interest burden is quantifiable, you can calculate the savings, and have a relatively low interest source of cash.
The second is what to get rid of. All due respect to @PeteB I'd wait before getting rid of any current cards for the reason above. I happen to use Credit Karma to track my score, and am able to see impact from adding a card or removing one. I carry no debt, and after getting a grip on the fact that running my expenses through credit cards will show a 'balance' so I pay in full before the balance is reported, I'm still careful with which accounts I'll add or remove. As long as the unused card carry no fee, I'd wait until after the mortgage is closed. Long term, the goal should be to have only cards that provide a unique benefit. I have one with 2% cash on all purchases. Another with 5% back on Amazon. Etc.
After you have your mortgage, I'd review the benefits of each card you have, and figure out a strategy moving forward. For example, the last card I got gave me $1200 worth of miles for my first $1000 worth of spending. (The kid transferred colleges, so that card may not be useful for long, but it was worth the effort for the return I got).
answered 2 hours ago
JoeTaxpayer♦JoeTaxpayer
148k23238478
add a comment |
Call me vain, but when it took me a ten minute phone call to get a $250K HELOC approved with no tax returns and no income (literally, we are retired), I'll wear my 850 FICO score on my hat.
You are in great shape. Be mindful of the factors that make up your score.
Adding the new card will -
- Lower your utilization
- Lower your credit history (# of years average account age)
- Add an inquiry/ New Credit
Killing an old card will
- Raise utilization
- Lower average account age
You really have 2 issues. The first is whether to get the new card. Yes. Of course. Lowering your current interest burden is quantifiable, you can calculate the savings, and have a relatively low interest source of cash.
The second is what to get rid of. All due respect to @PeteB I'd wait before getting rid of any current cards for the reason above. I happen to use Credit Karma to track my score, and am able to see impact from adding a card or removing one. I carry no debt, and after getting a grip on the fact that running my expenses through credit cards will show a 'balance' so I pay in full before the balance is reported, I'm still careful with which accounts I'll add or remove. As long as the unused card carry no fee, I'd wait until after the mortgage is closed. Long term, the goal should be to have only cards that provide a unique benefit. I have one with 2% cash on all purchases. Another with 5% back on Amazon. Etc.
After you have your mortgage, I'd review the benefits of each card you have, and figure out a strategy moving forward. For example, the last card I got gave me $1200 worth of miles for my first $1000 worth of spending. (The kid transferred colleges, so that card may not be useful for long, but it was worth the effort for the return I got).
answered 2 hours ago
JoeTaxpayer♦JoeTaxpayer
148k23238478
answered 2 hours ago
JoeTaxpayer♦JoeTaxpayer
148k23238478
answered 2 hours ago
JoeTaxpayer♦JoeTaxpayer
148k23238478
answered 2 hours ago
JoeTaxpayer♦JoeTaxpayer
148k23238478
148k23238478
add a comment |
add a comment |
Thanks for contributing an answer to Personal Finance & Money Stack Exchange!
- Please be sure to answer the question. Provide details and share your research!
But avoid …
- Asking for help, clarification, or responding to other answers.
- Making statements based on opinion; back them up with references or personal experience.
To learn more, see our tips on writing great answers.
Sign up or log in
StackExchange.ready(function ()
StackExchange.helpers.onClickDraftSave('#login-link');
);
Sign up using Google
Sign up using Facebook
Sign up using Email and Password
Post as a guest
Required, but never shown
StackExchange.ready(
function ()
StackExchange.openid.initPostLogin('.new-post-login', 'https%3a%2f%2fmoney.stackexchange.com%2fquestions%2f107949%2fimpact-on-credit-score-of-opening-and-closing-accounts%23new-answer', 'question_page');
);
Post as a guest
Required, but never shown
Sign up or log in
StackExchange.ready(function ()
StackExchange.helpers.onClickDraftSave('#login-link');
);
Sign up using Google
Sign up using Facebook
Sign up using Email and Password
Post as a guest
Required, but never shown
Sign up or log in
StackExchange.ready(function ()
StackExchange.helpers.onClickDraftSave('#login-link');
);
Sign up using Google
Sign up using Facebook
Sign up using Email and Password
Post as a guest
Required, but never shown
Sign up or log in
StackExchange.ready(function ()
StackExchange.helpers.onClickDraftSave('#login-link');
);
Sign up using Google
Sign up using Facebook
Sign up using Email and Password
Sign up using Google
Sign up using Facebook
Sign up using Email and Password
Post as a guest
Required, but never shown
Required, but never shown
Required, but never shown
Required, but never shown
Required, but never shown
Required, but never shown
Required, but never shown
Required, but never shown
Required, but never shown


2
Is the only reason you want to get the new card because it has a better rate? If you're paying off cards on time (as you should) and not carrying a balance, then the rate is inconsequential.
– Nosjack
4 hours ago
Care to share how you know your current score? Is it an actual FICO or an estimated one from a third party?
– JoeTaxpayer♦
3 hours ago